Mortgage decisions rarely happen in a vacuum.
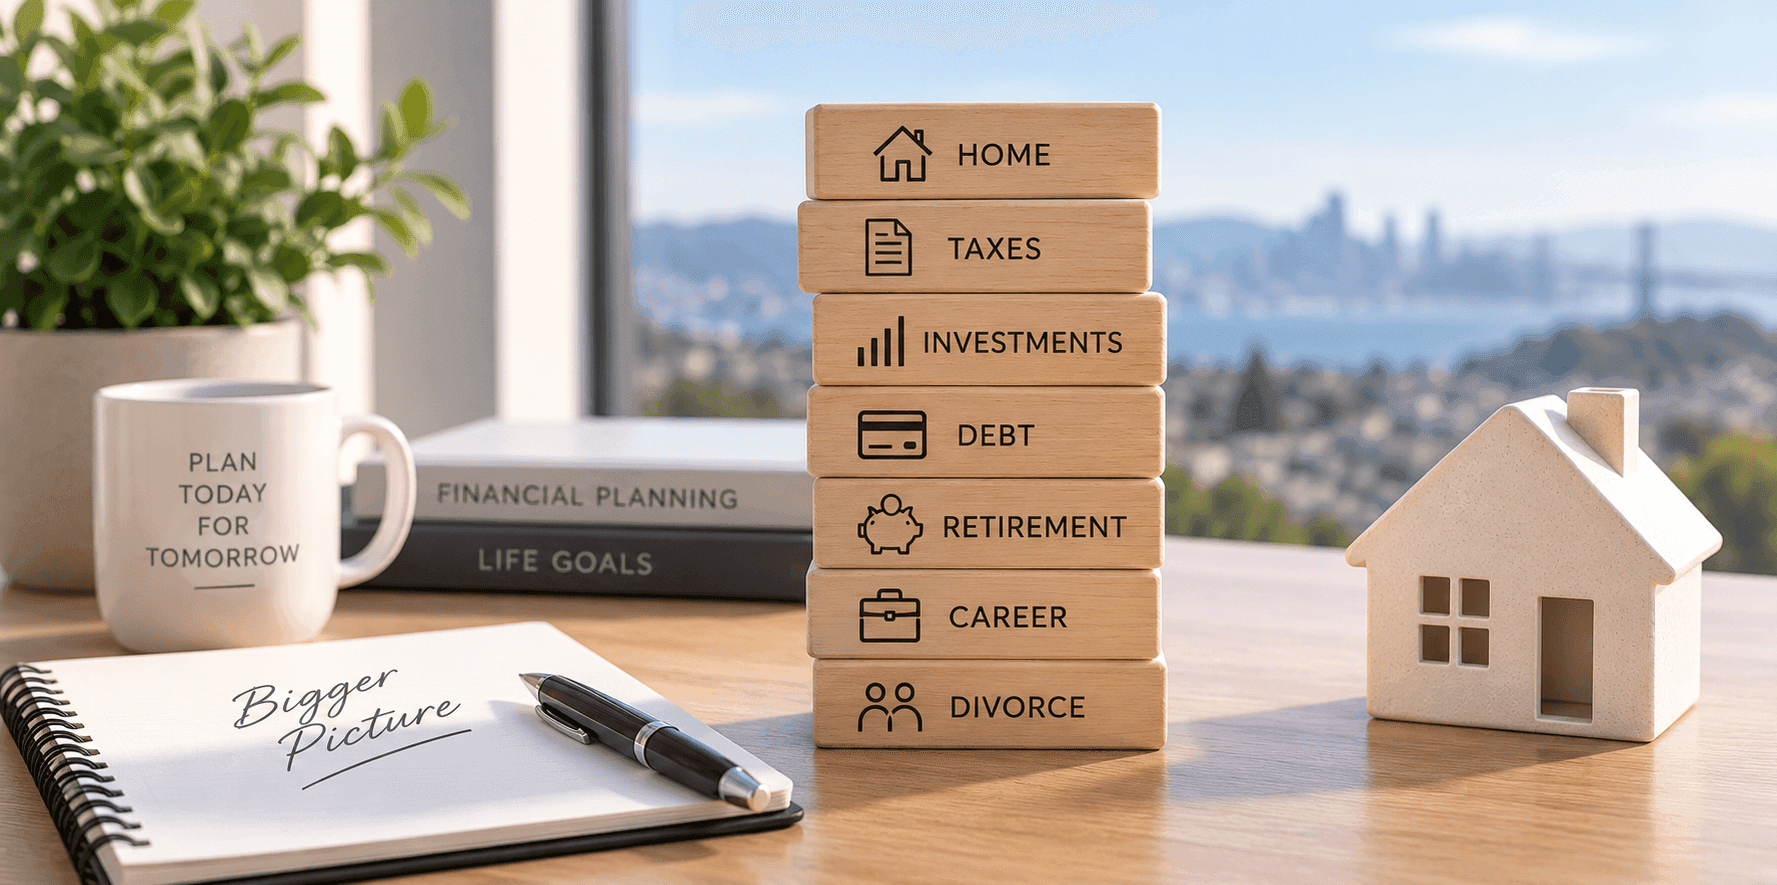
You may be thinking about buying a home or refinancing while also making decisions about your taxes, investments, debt, retirement, career, or family finances.
Each of those decisions may make perfect sense on its own.
But sometimes a change in one area can affect your options in another.
That's why good mortgage planning isn't simply about finding a loan.
It's about understanding how the mortgage fits into everything else you're trying to accomplish.
Tax planning can be particularly important for self-employed borrowers and business owners.
Reducing taxable income through legitimate business deductions may be an appropriate tax strategy. But depending on the circumstances, the income reflected on tax returns can also play a role in mortgage qualification.
That doesn't mean mortgage planning should drive your tax decisions.
It means that if buying or refinancing is one of your upcoming goals, your CPA or tax professional and mortgage professional may benefit from understanding what you're trying to accomplish before major decisions are made.
Sometimes simply knowing the mortgage implications ahead of time gives you more information to consider.
Perhaps you're considering moving money into an investment, selling assets, or changing your portfolio.
Those decisions may fit perfectly within your investment strategy.
But if you're also preparing to purchase a home, it's worth understanding how much cash you may need for the transaction and how much you want available afterward.
Your down payment is only one consideration.
Closing costs, reserves, future home expenses, and your other financial goals can all influence how much liquidity you want to maintain.
Looking at those pieces together can help prevent one goal from unintentionally interfering with another.
Paying off debt generally sounds like an obvious financial win.
And sometimes it is exactly the right move.
But if you're also preparing for a mortgage, it can be helpful to understand which use of your available cash may have the greatest impact.
Would eliminating a particular monthly payment improve your qualifying position?
Would paying down revolving debt potentially strengthen your credit profile?
Or would keeping some of that cash available for the home purchase leave you in a better overall position?
The answer depends on your individual financial picture.
A new job, promotion, or career opportunity may be a great financial move.
But changes in employment can also change the way income needs to be documented or evaluated for a mortgage.
This can be particularly important when compensation includes bonuses, commissions, overtime, equity compensation, or other variable income.
The point isn't to avoid making a career move because you may want a mortgage.
It's to understand whether the timing or structure of that change could affect your financing plans.
Retirement can involve several interconnected decisions.
When will employment income stop?
What income sources will replace it?
When will retirement distributions begin?
Will assets be repositioned?
If buying, refinancing, or making another housing change is also part of the plan, understanding how those decisions may affect mortgage qualification can be valuable.
A conversation before retirement may look very different from a conversation after the income structure has already changed.
Divorce is a particularly clear example of why financial decisions shouldn't always be evaluated independently.
The division of property, support, debt, retirement assets, and the marital home can all intersect.
If one spouse intends to keep the home, refinance, or purchase another property, the way certain parts of the settlement are structured may have mortgage implications.
Family law attorneys, financial professionals, tax professionals, and mortgage professionals each bring a different perspective.
When appropriate, collaboration before decisions are finalized can help the client understand how the pieces may work together after the divorce.
A CPA may be focused on tax efficiency.
A financial advisor may be focused on investments and long-term wealth.
An attorney may be focused on protecting the client's legal interests.
A Realtor® may be helping the client navigate a real estate transaction.
And a mortgage professional is evaluating how financial decisions may affect financing.
Each perspective is valuable.
The opportunity comes when those professionals understand the client's broader goal, rather than evaluating one decision completely independently of the others.
You don't need to wait until you've found a home or decided to refinance to start the mortgage conversation.
In fact, some of the most valuable planning can happen well before there's a transaction.
If you know a significant financial change is coming, understanding the potential mortgage implications beforehand can help you make a more informed decision.
There may be no conflict at all.
But if there is, it's much better to identify it while you still have options.
Your mortgage doesn't exist in a bubble.
Taxes, investments, debt, retirement, employment, divorce, and other financial decisions can all potentially intersect with your housing and financing goals.
That doesn't mean every decision should revolve around a mortgage.
It means the professionals advising you should understand what you're trying to accomplish as a whole.
Good mortgage planning should fit into your life and your other financial goals, not compete with them.
Janice Nugent is a Certified Mortgage Planning Specialist (CMPS®) and Certified Divorce Lending Professional (CDLP®) who helps California homebuyers and homeowners understand how mortgage financing fits into their broader financial picture.
Janice regularly works alongside Realtors®, family law attorneys, CPAs, financial professionals, and other trusted advisors to help clients consider the mortgage implications of important financial decisions before those decisions are made.
Janice provides mortgage planning and lending guidance and does not provide legal, tax, investment, or financial planning advice. Clients should consult the appropriate licensed professionals regarding those matters.
📩 Janice@JaniceNugent.com
☎ 925-683-0787
🌐 JaniceNugent.com
Our representative will be in touch with you.