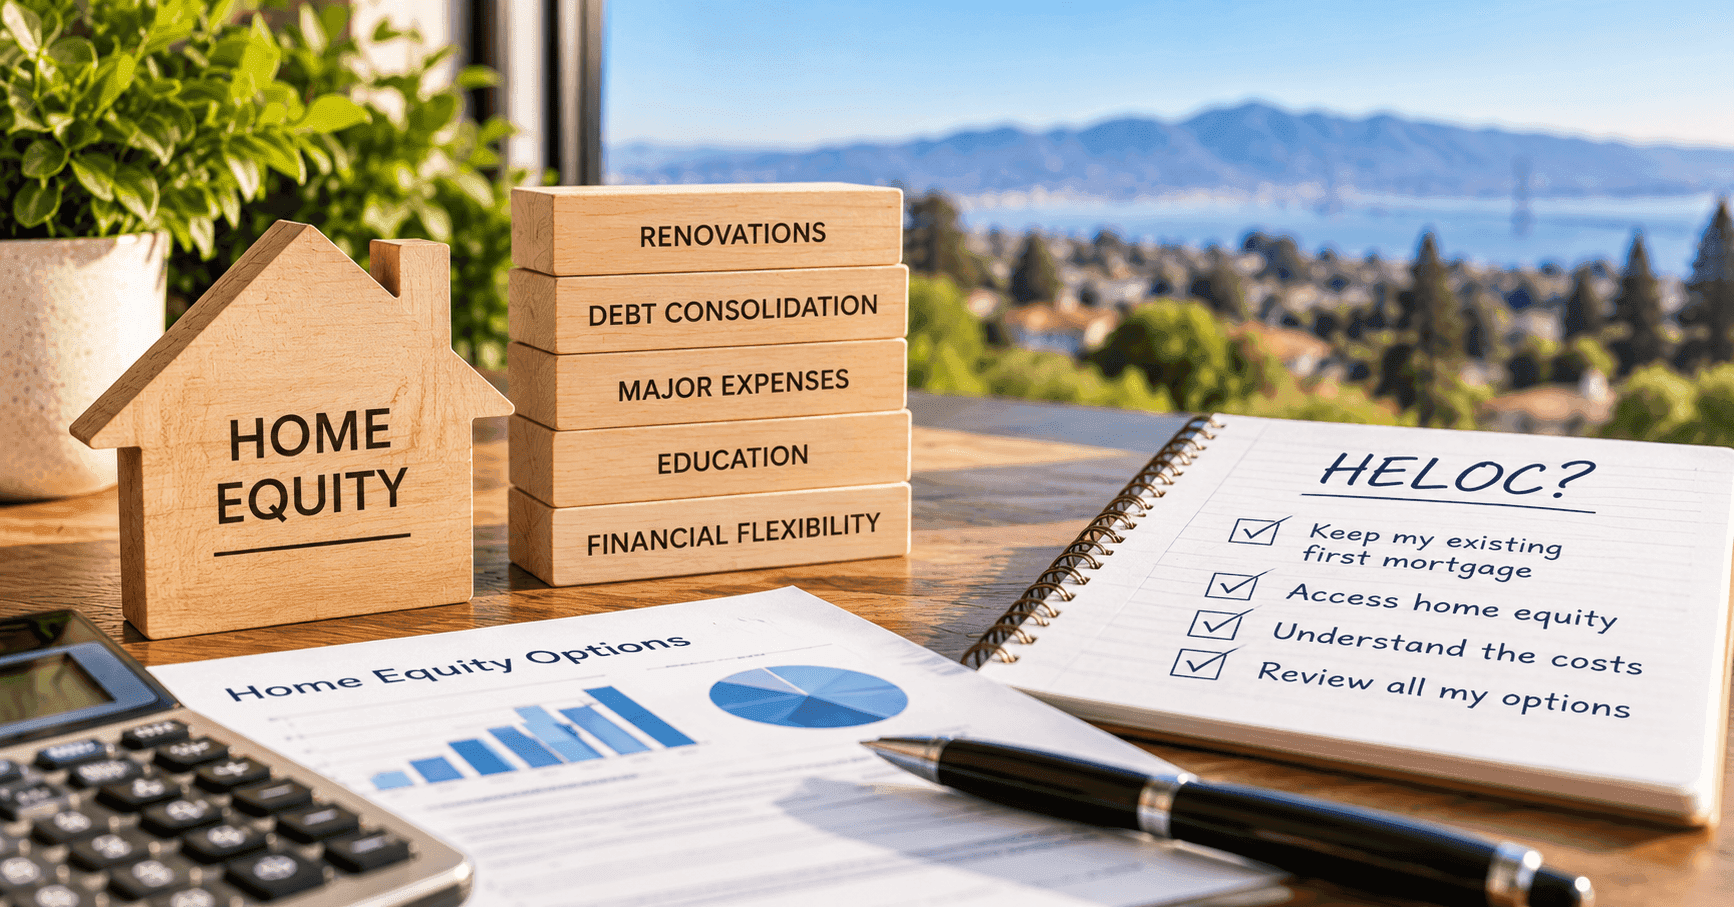
Homeowners have built substantial equity over the past several years, and more are finding ways to put some of it to work.
According to the June 2026 ICE Mortgage Monitor, second-lien lending reached an 18-year first-quarter high in Q1 2026. More than half, 54%, of all home equity extraction during the quarter came through second liens.Mortgage Tech
Why are more homeowners choosing this route?
For many, the answer comes down to their existing mortgage.
Millions of homeowners still have first mortgages with interest rates well below today's market levels.
If one of those homeowners needs to access equity, refinancing the entire mortgage through a cash-out refinance could mean replacing that lower-rate first mortgage with a new loan at today's rate.
A HELOC or other second-lien loan works differently.
It may allow a homeowner to borrow against available equity while leaving the existing first mortgage in place.
ICE found that nearly two-thirds of Q1 2026 second-lien originations came from borrowers whose first mortgages originated between 2020 and 2022, illustrating how strongly homeowners are trying to preserve those existing loans.
A Home Equity Line of Credit, or HELOC, is a revolving line of credit secured by your home.
Rather than receiving the entire loan amount at once, a HELOC generally allows you to borrow against an available credit line as needed during a specified draw period.
HELOCs commonly have variable interest rates, which means the rate and payment can change over time.
A fixed-rate home equity loan or other second mortgage may work differently, so it's important to understand the specific structure you're considering.
There isn't one reason homeowners tap their equity.
Someone might be considering funds for:
But having substantial home equity doesn't automatically mean borrowing against it is the right move.
Home equity is an asset. Borrowing against it creates a new debt secured by your home.
That's why the reason for accessing the money matters.
Both can provide access to home equity, but they do it very differently.
With a cash-out refinance, the existing first mortgage is replaced with a new, larger mortgage, and the homeowner receives a portion of the difference in cash.
With a HELOC, the existing first mortgage generally remains in place, while a separate line of credit is added against the property.
For a homeowner with a particularly attractive rate on their first mortgage, keeping that loan intact may be an important consideration.
But that doesn't automatically make a HELOC the better option.
The interest rate, payment structure, amount being borrowed, closing costs, repayment plans, and how long the homeowner expects to carry the debt can all affect the comparison.
A HELOC isn't the only way to access equity without replacing an existing first mortgage.
A fixed-rate second mortgage or home equity loan may provide a lump sum with a fixed interest rate and payment.
For someone who knows exactly how much they need and prefers a predictable payment, that structure may be worth comparing with a HELOC.
Again, the right structure depends on why you're borrowing and how you intend to repay it.
This is one of the most important differences to understand.
HELOCs are commonly variable-rate products, and their rates are often tied to the prime rate.
That means the cost of borrowing can move as short-term interest rates change.
ICE reported that average second-lien HELOC rates had fallen to 6.6% in March 2026, their lowest level since late 2022, which helped make home equity products more attractive to borrowers earlier this year.
But today's rate isn't necessarily tomorrow's rate.
Before opening a HELOC, understand how the rate is determined, whether there are introductory terms, how often the rate can adjust, and what the repayment period looks like.
This is where mortgage planning becomes important.
A homeowner may have significant available equity and still decide that borrowing against it doesn't make sense.
Another homeowner may determine that accessing a portion of their equity helps accomplish a specific goal while allowing them to preserve their existing first mortgage.
Before making that decision, I like to look at four things:
Why are you accessing the equity?
What will it cost?
How will it be repaid?
What other options may be available?
Looking at those questions together can provide a much clearer picture than simply asking, “How much can I borrow?”
HELOCs and other second liens are becoming more popular, particularly among homeowners who want access to their equity without replacing a low-rate first mortgage.
But popularity doesn't make a HELOC automatically right for every homeowner.
If you're considering tapping your home equity, compare the available options and understand how the new debt would fit with your existing mortgage and overall financial picture.
A HELOC can be a useful financial tool.
The important part is having a plan for why you're using it, what it will cost, and how you'll pay it back.
The home equity data referenced in this article comes from the June 2026 ICE Mortgage Monitor.
Read the June 2026 ICE Mortgage Monitor
Janice Nugent is a Certified Mortgage Planning Specialist (CMPS®) and Certified Divorce Lending Professional (CDLP®) who helps California homeowners and homebuyers understand how different mortgage and home equity strategies may fit their individual circumstances.
Janice works with clients and their professional advisors throughout California to evaluate mortgage options before important homeownership and financing decisions are made.
Janice provides mortgage planning and lending guidance and does not provide legal, tax, investment, or financial planning advice. Clients should consult the appropriate licensed professionals regarding those matters.
📩 Janice@JaniceNugent.com
☎ 925-683-0787
🌐 JaniceNugent.com